
Portfolio Lenders
Portfolio lenders offer mortgage solutions for borrowers who may not qualify for conventional financing. Unlike traditional lenders that sell most mortgages to investors, portfolio lenders keep certain loans in their own investment portfolios, allowing them to offer more flexible underwriting for borrowers with unique credit, income, or property situations. If you’ve been turned down by a bank because of bad credit, recent bankruptcy, self-employment income, or other qualifying challenges, a portfolio loan may provide a path to homeownership.
We have been helping home buyers and homeowners find specialized mortgage solutions since 2002. Over the years, we’ve built relationships with portfolio lenders across the country that offer programs for borrowers whose financial situations don’t fit traditional lending guidelines. Because every lender has different underwriting requirements, we take the time to understand your situation and help with the portfolio loan that best fits your needs.
Contact us here to discuss your portfolio loan options
What is a Portfolio Loan?
A portfolio loan is a mortgage that a lender holds onto in their investment portfolio after closing. Portfolio loans are non-conventional loans that do not meet Fannie Mae or Freddie Mac guidelines.
These loans do not meet conventional guidelines because the borrower has bad credit, a recent bankruptcy, or cannot fully document income. Since non-conventional loans are difficult to sell in the secondary market, these loans are kept within the lender’s portfolio which is why they are called portfolio loans.
The most popular portfolio loan today is the bank statement loan. This loan program was created for self-employed individuals who cannot qualify using the net income on their tax returns.
Who Should Consider a Portfolio Loan?
Individuals who may have or need one or more of the following may want to consider a portfolio loan.
- Self-employed business owners
- Independent contractors
- Gig workers
- Real estate investors
- Recent Chapter 7 bankruptcy
- Chapter 13 bankruptcy
- Recent foreclosure
- Short sale
- ITIN borrowers
- Foreign nationals
- High debt-to-income ratios
- Bank statement borrowers
- Asset depletion borrowers
- Jumbo borrowers
- Unique properties
- Borrowers with multiple financed properties
Portfolio Lenders: Flexible Mortgage Solutions for Borrowers with Unique Financial Situations
A portfolio lender is a financial institution that keeps certain mortgage loans in its own investment portfolio instead of selling them on the secondary mortgage market. Because portfolio lenders assume the long-term risk of these loans, they often have greater flexibility when evaluating borrowers who may not meet conventional lending guidelines. Portfolio loans can be an excellent option for self-employed borrowers, real estate investors, individuals with recent credit challenges, high debt-to-income ratios, unique properties, or borrowers who need alternative income documentation.
We have been helping home buyers and homeowners explore mortgage solutions since 2002. Over the years, we’ve built relationships with portfolio lenders across the country that offer specialized loan programs designed for borrowers whose financial situations don’t always fit traditional underwriting guidelines. Rather than taking a one-size-fits-all approach, we work to understand your individual circumstances and help identify lenders that may offer financing options tailored to your needs.
Whether you’re purchasing your first home, refinancing an existing mortgage, buying an investment property, or recovering from a financial hardship, understanding how portfolio lending works can help you determine whether this type of financing is the right solution for you.
Click to speak with a portfolio experienced loan officer
Why Borrowers Choose Portfolio Lenders
Many borrowers assume that if one bank declines their mortgage application, every lender will reach the same decision. In reality, lending guidelines can vary significantly from one institution to another.
Portfolio lenders have the ability to make lending decisions based on their own underwriting standards because they retain certain loans instead of selling them to investors. This flexibility allows some portfolio lenders to approve borrowers whose financial situations fall outside traditional mortgage guidelines.
A portfolio loan may be worth considering if you have:
- Recent bankruptcy or foreclosure
- Self-employment income
- 1099 income
- Bank statement income
- High debt-to-income ratio
- Credit challenges
- Multiple financed properties
- Jumbo loan financing needs
- Non-warrantable condominium
- Mixed-use property
- Rural property
- Unique income sources
- Asset depletion income
- Foreign national status
- ITIN documentation
Not every portfolio lender offers every type of loan, which is why comparing available programs is often one of the most important steps in the mortgage process.
How Portfolio Lenders Are Different From Traditional Mortgage Lenders
Many consumers wonder what makes a portfolio lender different from a conventional mortgage lender. The biggest difference is what happens after the loan closes.
Traditional lenders often sell their loans to investors on the secondary mortgage market. Because those loans must meet strict underwriting guidelines established by government-sponsored enterprises or investors, borrowers are expected to satisfy standardized requirements for credit, income, assets, and property eligibility.
Portfolio lenders, on the other hand, may choose to keep certain loans in their own investment portfolios. Since they continue servicing or holding the loan, they often have greater flexibility when evaluating applications involving unique financial situations.
While portfolio loans still require responsible underwriting and borrowers must demonstrate an ability to repay the loan, the approval process may consider factors that conventional financing does not.
| Traditional Mortgage | Portfolio Loan |
|---|---|
| Often sold after closing | Often retained by lender |
| Standard underwriting | More flexible underwriting |
| Limited exceptions | Greater case-by-case flexibility |
| Traditional income documentation | Alternative documentation may be accepted |
| Standard property guidelines | Some unique property types may qualify |
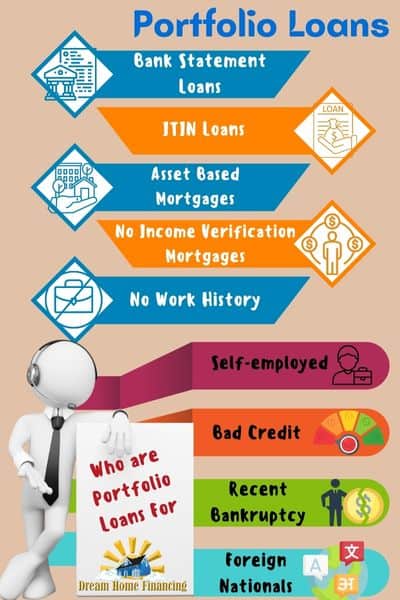
Who are Portfolio Loans For?
If you have good credit, can document your income, and down payment money to qualify for a conventional or government mortgage, then a portfolio lender is probably not what you are looking for. However, if any of the situations below apply to you, then a portfolio lender can likely help you with your mortgage.
- Bankruptcy discharged less than two years ago
- Foreclosure within the past three years
- Bad credit scores
- Recent late payments on another mortgage
- Tax liens or judgements
- Self-employed
- Unable to provide tax returns
- Foreign nationals with no social security number
Types of Portfolio Loans
There are various types of mortgages that are considered to be “portfolio loans” which are not offered by must local banks. These portfolio loans are for special circumstances for borrowers who are unable to get approved by conventional lenders.
Bank Statement Loans – Bank statement loans are for self employed home buyers who cannot qualify because they write off too much on their tax returns. The portfolio lenders who offer this program will evaluate their application based upon the average monthly deposits into the bank statements. Read more about bank statement loans.
ITIN Loans – Immigrants who have an ITIN instead of a social security number can qualify for this mortgage to purchase or refinance a home. ITIN card holders otherwise would not qualify for a conventional or FHA loan due to their residency status. Read more about ITIN loans.
Recent Bankruptcies – Home buyers with a recent Chapter 7 or Chapter 13 bankruptcy can qualify for this type of bankruptcy portfolio loan when other lenders would ask for a long waiting period. A mortgage after a bankruptcy is possible just one day after your discharge.
Asset Based Mortgages – Mortgages that look at liquid assets rather than income are called asset depletion loans. Lenders will look at your net liquid assets to determine how much you will qualify for.
No Income Verification Mortgages – No income verification or no doc loans are for applicants who cannot or prefer not to document their income. The down payment and interest rates will be higher than a conventional loan.
No Work History – If you do not have a two year work history, you may apply for a portfolio loan that does not require the two years. It is a similar program to the no income verification mortgage. Credit scores and assets will be an important factor in your ability to qualify.
Pros and Cons of Portfolio Loans
There are advantages and disadvantages associated with portfolio loans. We will out line the most common facts that you need to know before you decide whether a portfolio loan is right for you.
Pros
- Can qualify with lower credit scores
- Can get approved with a recent bankruptcy, foreclosure or short sale
- Typically no PMI for down payments less than 20%
- Debt to income ratios can be higher
- No tax returns needed
Cons
- Interest rates higher than conventional mortgages
- Pre-payment penalties for investment properties likely
- Higher lender fees
Keep in mind that these pros and cons may not apply to every portfolio lender or portfolio loan. These are also just a few examples of portfolio lenders we work with. Their guidelines and product offerings change often.
What Makes a Strong Portfolio Loan Application?
Although portfolio lenders often provide greater underwriting flexibility, borrowers should still prepare a strong mortgage application.
Lenders generally evaluate:
- Credit history
- Employment stability
- Income consistency
- Available assets
- Down payment
- Cash reserves
- Property type
- Occupancy
- Overall ability to repay
Even if your credit score is lower than ideal, strengths in other areas of your application may improve your approval chances.
Portfolio Loan Interest Rates
One of the cons of a portfolio loan will be interest rates that are a bit higher than conventional or government loans. Each lender will have different rates based upon their need to offset the risk of keeping the loans within their own investment portfolios.
The down payment amount and credit scores are two major factors that determine your interest rate. The more you put down and the higher your interest rate, the lower your interest rate will be.
Some portfolio lenders either require a larger down payment or charge a higher interest rate for lending in areas they consider to be higher risk. Two examples of high risk lending locations are Chicago and New York.
The bottom line is that you can buy your dream home with a portfolio loan and your interest rate will be slightly higher than what you would get with a conventional loan.
Portfolio Loan Fees and Closing Costs
One of the things you need to expect with a portfolio loan is higher lender fees. You may see origination fees of up to 2% and possibly points as well. Underwriting fees and other lender based fees are likely but some of these fees are also common with conventional loans.
Plan on budgeting anywhere from 2%-5% of the loan for closing costs which include the lender fees.
Investment or Rental Portfolio Loans
Portfolio loans are also available for investment properties. For investment properties, portfolio lenders may require a larger down payment than what would be required for a primary residence.
Investment property portfolio lenders will help you with residential 1-4 unit properties. In some instances, you may be able to qualify based upon the future cash flow of the building. Let us connect you with one of our portfolio lenders to discuss your options.
Frequently Asked Questions About Portfolio Lenders
What is a portfolio lender?
A portfolio lender is a financial institution that retains certain mortgage loans in its own investment portfolio instead of selling them to investors. This allows the lender to establish underwriting guidelines that may be more flexible for qualified borrowers.
Are portfolio loans harder to qualify for?
Not necessarily. While portfolio loans still require borrowers to demonstrate the ability to repay the loan, they may provide financing options for borrowers who do not meet conventional mortgage guidelines.
Are interest rates higher?
Interest rates vary depending on the lender, loan program, credit profile, down payment, and overall risk. Some portfolio loans may have slightly higher interest rates than conventional mortgages because of the increased flexibility they offer.
Can self-employed borrowers qualify?
Yes. Many portfolio lenders offer bank statement loans and other alternative documentation programs specifically designed for self-employed borrowers.
Can I qualify after bankruptcy?
Some portfolio lenders offer financing sooner than conventional mortgage programs after a bankruptcy discharge, provided other underwriting requirements are met.
Can portfolio loans be used for investment properties?
Yes. Many portfolio lenders offer financing for investment properties, including single-family rentals, multi-unit properties, and certain commercial real estate.
Summary
Every borrower’s financial situation is different, which means the best portfolio lender for one borrower may not be the best choice for another. Factors such as your credit history, employment, income documentation, property type, down payment, and long-term financial goals all play an important role in determining which loan program may be the best fit.
Since 2002, Dream Home Financing has helped borrowers across the country explore mortgage options for situations that don’t always fit conventional lending guidelines. We understand that many borrowers come to us after being told “no” elsewhere, and our goal is to help identify lenders and loan programs that better align with each borrower’s unique circumstances.
If you’re considering a portfolio loan, taking the time to review all available options with an experienced mortgage professional can help you make a more informed decision and increase your confidence throughout the home financing process.
We can help you to find a portfolio mortgage option in the following states: Alabama, Alaska, Arizona, Arkansas, California, Colorado, Connecticut, Delaware, Florida, Georgia, Hawaii, Idaho, Illinois, Indiana, Iowa, Kansas, Kentucky, Louisiana, Maine, Maryland, Massachusetts, Michigan, Minnesota, Mississippi, Missouri, Montana, Nebraska, Nevada, New Hampshire, New Jersey, New Mexico, New York, North Carolina, North Dakota, Ohio, Oklahoma, Oregon, Pennsylvania, Rhode Island, South Carolina, South Dakota, Tennessee, Texas, Utah, Vermont, Virginia, Washington, West Virginia, Wisconsin, Wyoming